If you've looked at UK rental yields recently, the North East is hard to miss. It sits at the top of nearly every table. That attracts a lot of first-time investors to the region, and a fair few of them buy the wrong thing.
Why the region tops the tables
The North East is the strongest yield region in the UK on both major lender surveys: Fleet Mortgages puts it highest nationally at 9.2% in Q2 2026, and Paragon Bank has it tied for second nationally, with Scotland, at 7.97%, both behind Wales. Rents are also moving faster here than nationally, with ONS figures putting North East rental inflation at 5.8% in the year to August 2026, tied with the North West, against 4.0% for England as a whole.
Where the headline number breaks down
That 7.9% is a gross figure covering the entire region, and it's pulled upwards by the region's cheapest stock. It is not the yield you'll see in the stronger residential postcodes, where purchase prices sit well above the regional average. Gross also ignores Section 24 tax treatment, management fees, mortgage interest and the additional-property stamp duty surcharge, so net returns typically land 1.5 to 2.5 percentage points lower once running costs are accounted for.
Different sources also measure it differently. Fleet Mortgages put the North East highest in the country at 9.2% in Q2 2026; Paragon Bank has it tied for second nationally - neither shows the yield on a specific house on a specific street.
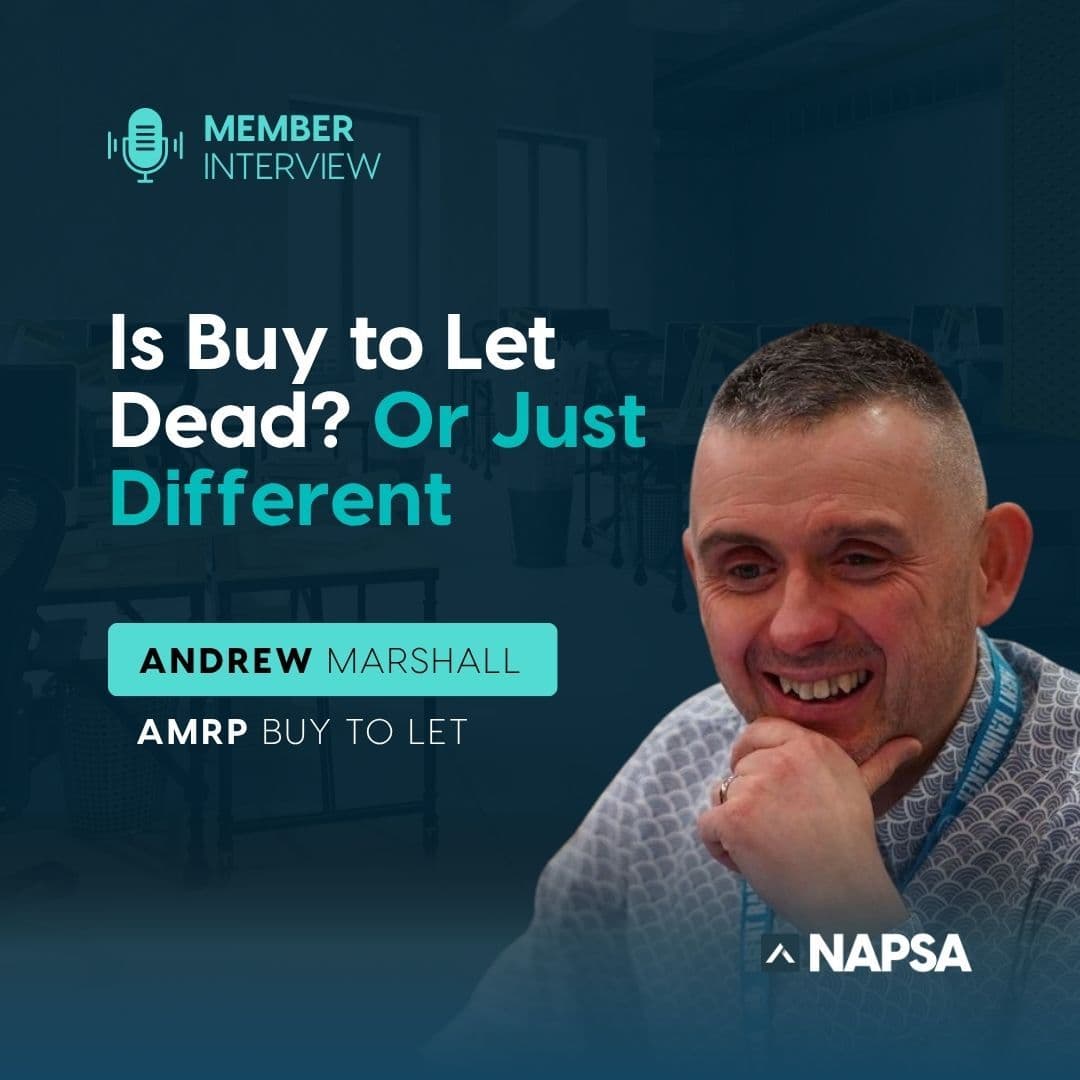
That's Andrew Marshall's point in the interview, from close to two decades of managing tenancies across these postcodes: investors never find success unless they define what success looks like at the outset, specifically to them. A yield percentage isn't a strategy. It's an output.
The high-yield trap
The very highest-yielding North East postcodes are high-yielding because median sale prices sit below £70,000. Before targeting one, it's worth checking transaction volumes, leasehold mix and, most importantly, whether tenant demand is genuinely durable or concentrated in a single employer or sector. Small secondary towns and coastal areas in the region face ongoing population decline, which doesn't show up anywhere in a yield figure.
A cheap property with a big number attached isn't automatically a good investment. It's a good investment if it lets reliably, for years, to tenants who stay.
Where the region's story has substance
Not all of it is cheap-stock arithmetic. Sunderland in particular now has a credible employment and infrastructure story behind its yield figures, the Nissan and EV manufacturing cluster being the clearest example, which is a materially different proposition to a low price on its own.
The wider region spans very different markets: Darlington, Sunderland, Newcastle upon Tyne, County Durham, Teesside and Hartlepool don't behave alike, and treating "the North East" as one market is where a lot of remote investors go wrong.
What to do before you buy here
Andrew's advice to first-time North East investors is unglamorous and worth repeating: go and see the property in person. Remote buying off a spreadsheet and a yield table is how people end up owning a house on a street they'd never have bought on had they stood in it. If you genuinely can't visit, insist on proper evidence, a full, timestamped inspection report covering every room inside and out, not three estate agent photos.
And work out what you're trying to achieve before you look at deals, not after. Income now, capital growth later, or a portfolio you can eventually pay down: those point at different properties in different parts of this region.
For a fuller picture of the North East market from someone who's worked it since 2002, watch our interview with Andrew Marshall of AMRP Buy To Let Advisory Services, a NAPSA-accredited sourcing agent covering Darlington, Sunderland, Newcastle upon Tyne, County Durham, Teesside and Hartlepool.
Get in touch with AMRP
To find out more about how AMRP Buy To Let Advisory Services works with landlords and investors, or to speak to Andrew's team directly, visit their NAPSA profile or call 0191 640 4604. You can also find them at amrp.co.uk.
Frequently asked questions
Why are rental yields so high in the North East?
Property prices in the region are the lowest in the UK, around £114,098 on average for a buy-to-let, while rents remain solid at roughly £748 a month. That price-to-rent ratio produces high gross yields. Yields above 7% are consistent across County Durham and Tyne and Wear, whereas London and the South East rarely exceed 4%.
Is a high gross yield the same as a good return?
No. Gross yield ignores tax treatment under Section 24, management fees, mortgage interest, maintenance and the stamp duty surcharge on additional properties. Net returns are usually 1.5 to 2.5 percentage points lower. High-yield areas also tend to see more modest capital growth, so the profile suits income-focused investors more than growth-focused ones.
Which North East areas are best for buy-to-let?
There's no single answer. Darlington, Sunderland, Newcastle upon Tyne, County Durham, Teesside and Hartlepool are distinct markets with different tenant bases and price points. Sunderland stands out on yield and has genuine employment growth behind it, but the right area depends entirely on your strategy.
Can I invest in the North East if I live elsewhere in the UK?
Yes, and many investors do. The key is not buying blind: visit where you can, and where you can't, require thorough timestamped evidence of the property's condition. A locally-based NAPSA-accredited sourcing agent can also provide the on-the-ground knowledge a yield table can't, however what "works" for you will come down to your own calculations and longer-term strategy.
In this article
- Why the region tops the tables
- Where the headline number breaks down
- The high-yield trap
- Where the region's story has substance
- What to do before you buy here
- Get in touch with AMRP
- Frequently asked questions
- Why are rental yields so high in the North East?
- Is a high gross yield the same as a good return?
- Which North East areas are best for buy-to-let?
- Can I invest in the North East if I live elsewhere in the UK?